The §754 Election: Family LLC Operating Agreements

Mario Bai
Why the step-up in basis your heirs are counting on may never reach the assets that actually matter, and how the operating agreement can secure it.
Ask any estate planning attorney what happens to appreciated assets at death, and you'll get the textbook answer: the heirs receive a "step-up" in basis to fair market value, and decades of built-in capital gain quietly disappears. That answer is correct and, for families who hold their wealth inside an LLC or family partnership, dangerously incomplete.
Here is what the textbook answer misses: when a member of a Family LLC dies, the basis step-up attaches to the membership interest, not to the real estate, securities, or operating assets inside the entity. Unless the LLC has a valid election in effect under Section 754 of the Internal Revenue Code, the gain your family spent a generation building doesn't disappear at death. It simply goes dormant, waiting inside the entity for the day the heirs sell, at which point they pay capital gains tax on appreciation that, economically, was already extinguished.
That single omission can cost a family more than the entire federal estate tax the plan was designed to avoid.
Two Bases, One Asset
Partnership taxation, which governs most multi-member LLCs, runs on a dual-basis system that most planning never engages with:
Outside basis is what each member has in their membership interest itself. When a member dies, Section 1014 steps this up to fair market value automatically, provided the interest is included in the member's gross estate. This is the step-up everyone knows about. (An interest held in an irrevocable grantor trust outside the estate receives no step-up at all; see Rev. Rul. 2023-2. In that case, there is no basis increase for a §754 election to carry inside.)
Inside basis is the LLC's own basis in the assets it holds: the buildings, the brokerage account, the operating company. Death does nothing to inside basis. By default, it stays exactly where it was, no matter how many members die holding interests in the entity.
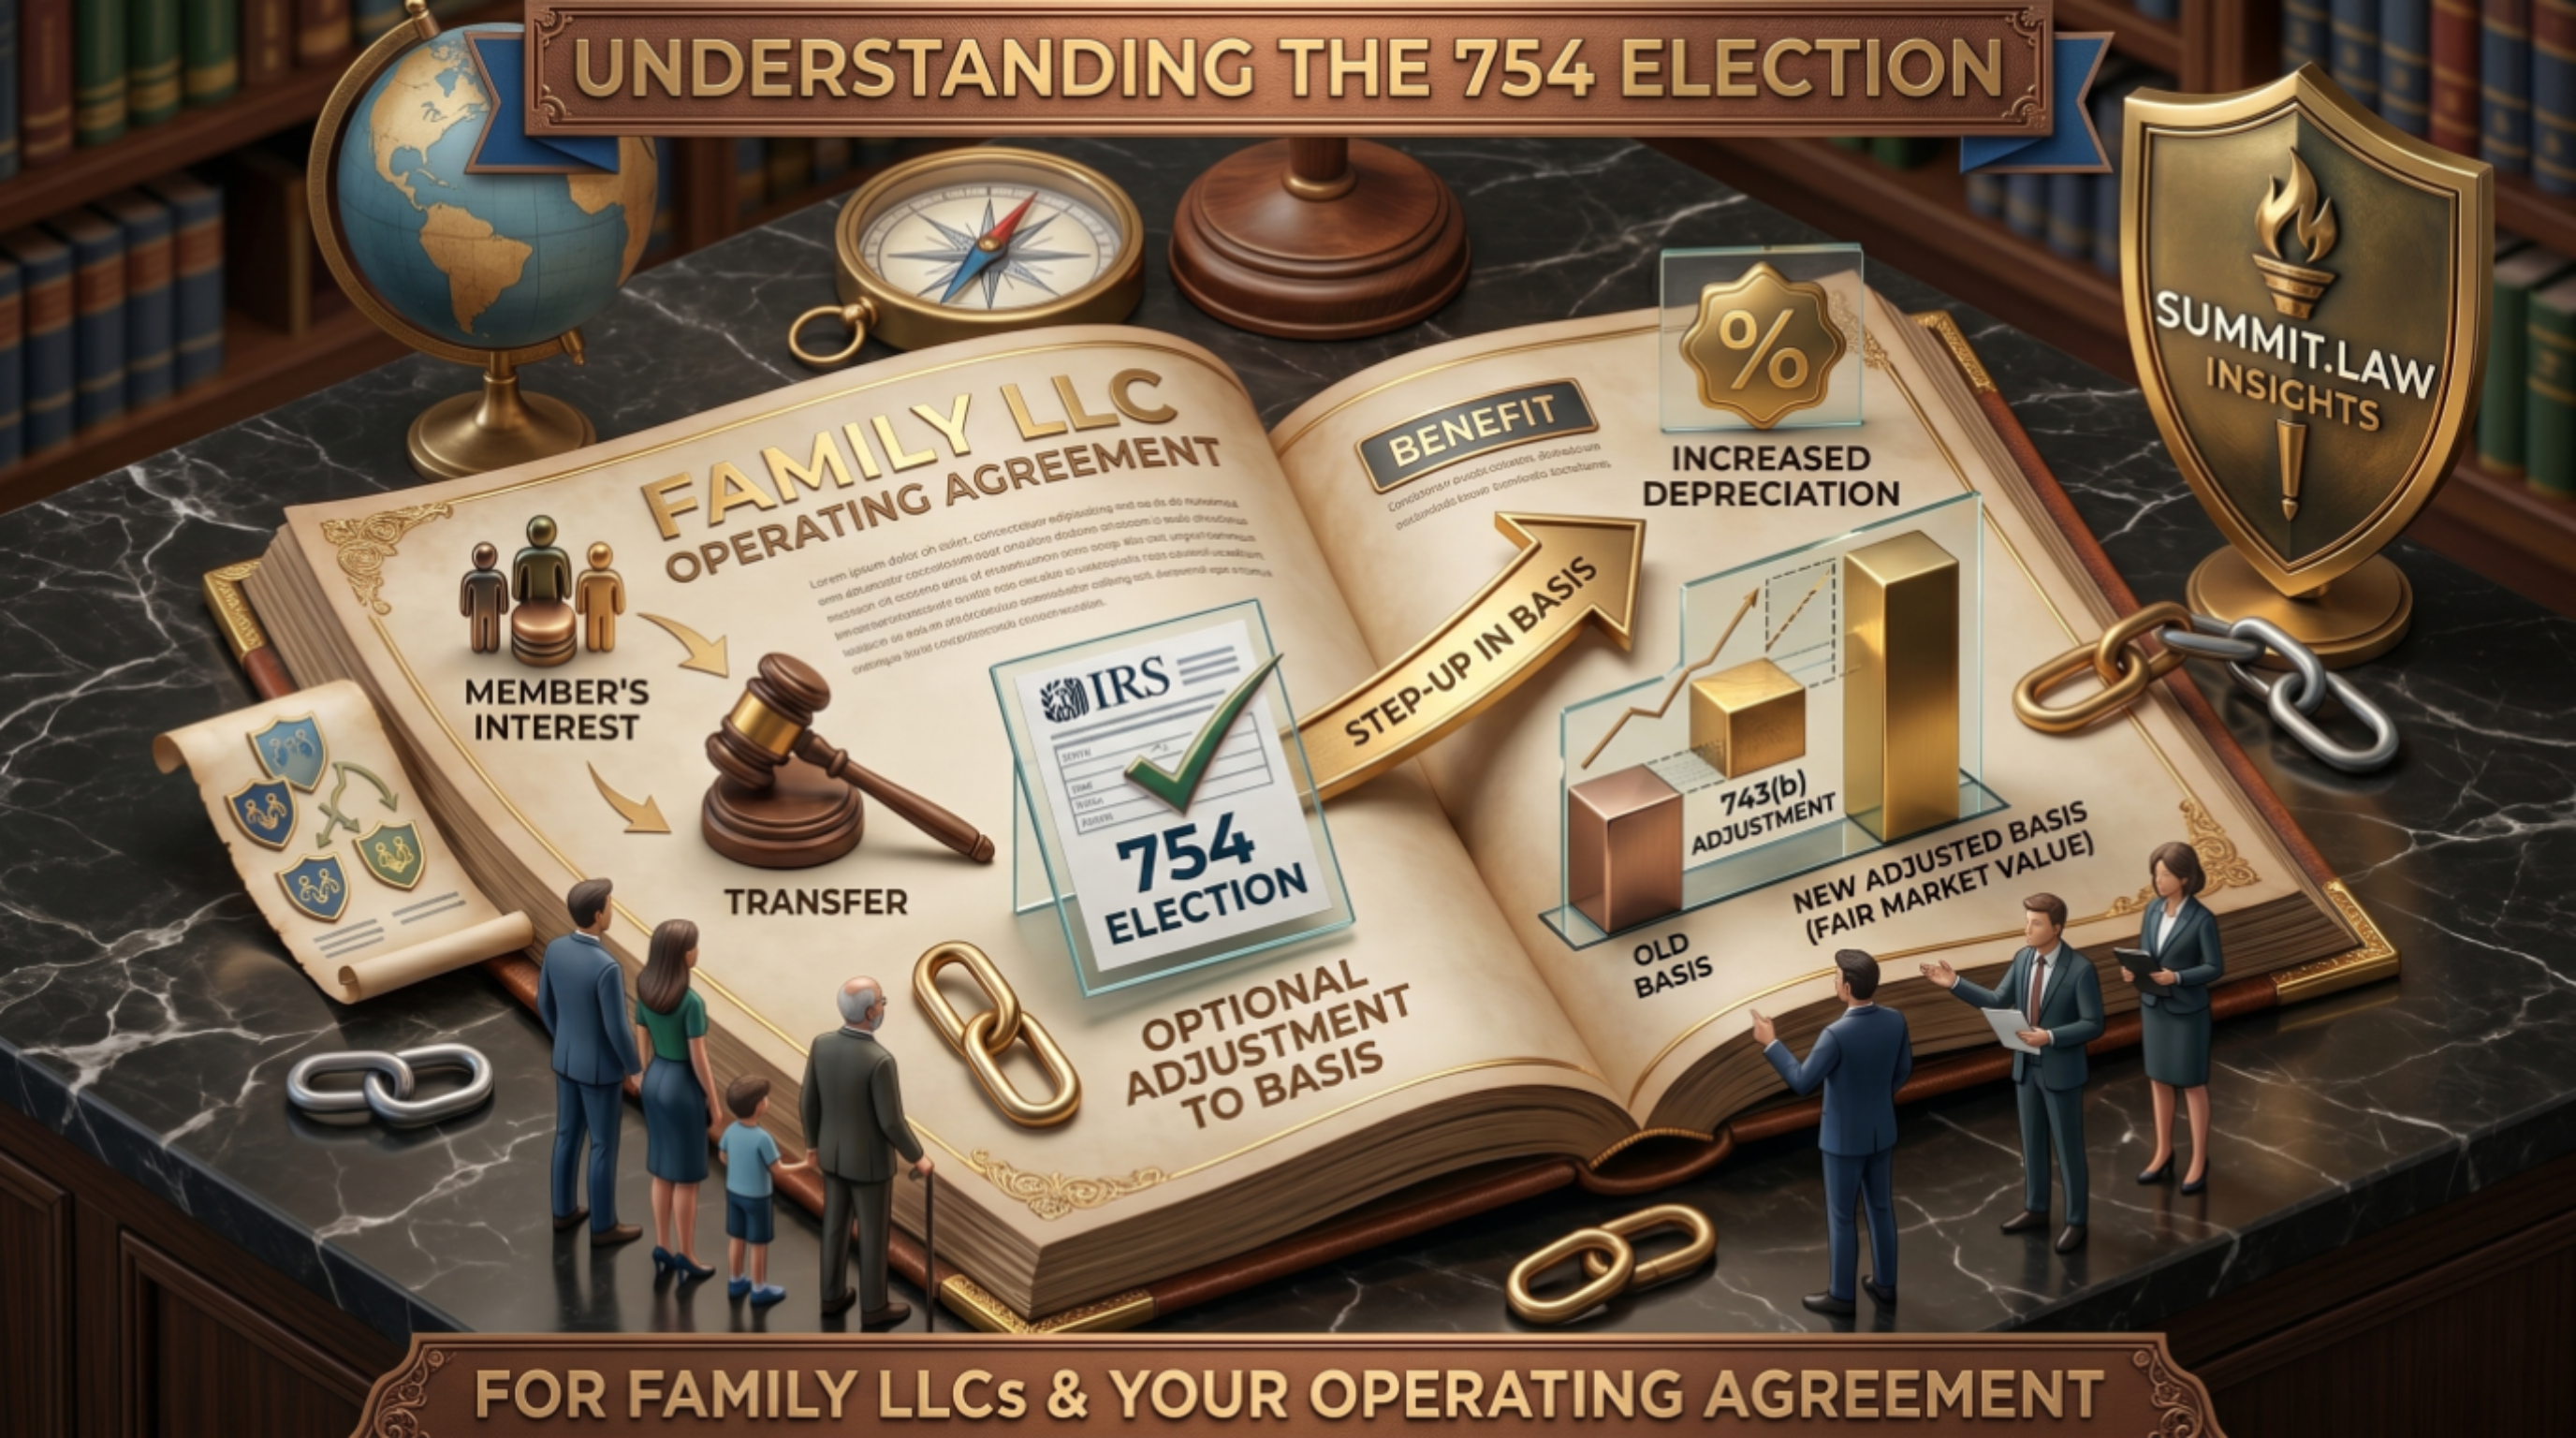
The result is a structural mismatch: the heir's outside basis says "no gain here," while the entity's inside basis preserves every dollar of historic appreciation. The Code's bridge across that gap is the Section 754 election, which unlocks a basis adjustment under Section 743(b), stepping up the inside basis of the LLC's assets, but only with respect to the deceased member's transferred interest, and only if the election is actually in place.
What the Mismatch Costs: A Working Example
Consider a common South Florida structure: a Family LLC holding commercial real estate worth $20 million, with a depreciated inside basis of $4 million. The founding member, call him the patriarch, owns 50%, and his outside basis in that interest is $2 million. For now, assume no valuation discount applies to his interest (more on that below).
At his death, without a §754 election:
His daughter inherits the 50% interest with an outside basis stepped up to $10 million. On paper, the step-up worked. But two years later, the family decides to sell the building. The LLC recognizes $16 million of gain, and $8 million of it is allocated to the daughter: gain on appreciation that occurred entirely before her father's death, appreciation the estate tax system already valued and the income tax system was supposed to forgive. At top federal rates, that is roughly $1.9 million to $2.3 million of tax on phantom gain, depending on how much of it is unrecaptured §1250 gain taxed at 25% rather than 20%, and assuming the 3.8% net investment income tax applies. (Her stepped-up outside basis eventually produces an offsetting loss: capital, deferred, and frequently stranded where she can't use it.)
With the election in place:
The §743(b) adjustment steps up the inside basis of the LLC's assets by $8 million (her $10 million outside basis minus her $2 million share of inside basis), but solely for the daughter's benefit. When the building sells, her share of the gain is largely eliminated; the only gain that returns is the portion of the adjustment she has already recovered through depreciation.
And if the family doesn't sell, the result is arguably better still. Under Treas. Reg. §1.743-1(j)(4), the portion of her adjustment allocated to the building is treated as newly purchased property placed in service at the time of the transfer and depreciated straight line over a fresh 39-year recovery period. Because the adjustment is spread across the LLC's assets under §755, and land is not depreciable, the building's share is what matters: if $6 million of her adjustment lands on the building, that is roughly $154,000 per year in new deductions against the property's income, available only to her. The election doesn't just prevent a tax; it manufactures an ongoing income tax asset.
In this example: one statement on one return, and seven figures of swing.
Why the Election Gets Missed
If the election is this valuable, why is it so routinely absent? Because it lives in a jurisdictional gap between professions.
The election is made by the LLC, not by the estate, in a written statement filed with the partnership's timely filed return (including extensions) for the year of the transfer. The estate planning attorney drafts the trust and the will; the CPA prepares the 1065 from last year's workpapers; nobody's engagement letter covers the question of whether the operating agreement even permits the election, or who has the authority to compel it. In families where the surviving members and the deceased member's heirs have diverging interests (and after a death, they often do), a manager with no contractual obligation to make the election can simply decline.
There is a safety valve, but it is narrow. The §754 election is one of the regulatory elections eligible for an automatic 12-month extension under Treas. Reg. §301.9100-2, and relief beyond that may be available by private letter ruling under §301.9100-3. Relief is a repair, not a plan, and it still requires someone with the authority to act.
There are also legitimate reasons for caution that demand actual analysis rather than a reflexive yes. The election applies to every future transfer and distribution, not just the one in front of you, and it can be revoked only with IRS approval, which the regulations provide will not be granted where the primary purpose is to avoid a basis step-down. It imposes real ongoing accounting complexity, because §743(b) adjustments are tracked transferee by transferee. And the knife cuts both ways: where assets have declined in value, the adjustment runs downward, and under §743(d), a downward adjustment is mandatory when there's a substantial built-in loss, election or no election.
This is precisely the kind of decision that should be architected in the operating agreement at formation: mandating the election (or vesting the authority clearly), allocating the accounting burden, and aligning the manager's duties with the family's basis strategy. It should not be improvised by a grieving family against a tax return filing deadline.
The Discount Trap: Where Old Planning Collides With New Law
There is a second-order issue here, and it cuts against a long-standing playbook. The §743(b) adjustment equals the heir's outside basis in the transferred interest minus her share of the LLC's inside basis, which means every valuation discount applied to that interest at death directly shrinks the adjustment available to her. In the example above, a 35% discount would cut the daughter's outside basis from $10 million to $6.5 million, and her §743(b) adjustment from $8 million to $4.5 million.
For twenty years, the standard playbook was to layer lack-of-control and lack-of-marketability discounts onto family entity interests to compress estate values. That made sense when the estate tax was the predator. But for 2026, the federal basic exclusion amount is $15 million per person, indexed for inflation beginning in 2027, with no scheduled sunset. A married couple can shelter $30 million with a portability election or proper credit shelter planning. For the substantial majority of families holding wealth in entity structures, the federal estate tax is no longer the binding constraint. Income tax is. A 35% discount that saves zero estate tax for an exempt estate, while permanently forfeiting millions in basis step-up, is not conservative planning. It is an unforced error executed with great formality.
State estate tax changes the math. New York, for example, imposes its own estate tax with an exclusion well below the federal amount, and a New York taxable estate that exceeds that exclusion by more than 5% loses the benefit of the exclusion entirely. For New York domiciliaries, discounts can still earn their keep.
The modern analysis asks a different question entity by entity, asset by asset: where is this family's real tax exposure, federal and state, and is the structure engineered to maximize basis where the estate tax no longer bites, while preserving compression where it still does?
The Architecture View
The §754 election is not exotic. It is black-letter partnership tax. What is rare is the discipline to integrate it at the drafting stage with the valuation strategy, the trust design, the depreciation profile of the underlying assets, and the family's actual exposure under the current exemption regime. That integration is what turns a set of estate planning documents into a tax architecture.
If your family's wealth sits inside an LLC or partnership and you cannot say, today, whether a §754 election is in place, who controls it, and what it would be worth at the next transfer, that is a conversation worth having before the next transfer happens.
Summit Law Group, PLLC advises ultra-high-net-worth individuals, family offices, and founders on tax, trust, and structural planning across Florida, New York, and New Jersey. This article is for general information only and does not constitute legal or tax advice. The example above is hypothetical and illustrative; the application of §754 and §743(b) depends on facts specific to each entity and transfer.